Crypto enters the week on steadier footing, with Bitcoin having closed the prior week near $84,650 after a weak U.S. jobs report reset expectations for the Federal Reserve. The calendar, not the tape, drives the next five days: the industry decamps to Singapore for TOKEN2049, the Fed’s September minutes land midweek, Ethereum takes another step toward its Glamsterdam upgrade, and a closely watched XRP treasury vehicle aims to begin trading on Nasdaq.
Three things frame the week. The macro backdrop has turned dovish: the September employment report, released October 2, showed the U.S. added just 29,000 jobs against expectations near 90,000, with unemployment ticking up to 4.2%, a soft print that sharply lowered the odds of another rate hike at the Fed’s next meeting. There is no new rate decision this week; the main macro event is Wednesday’s FOMC minutes. On supply, Hyperliquid’s monthly HYPE tranche on Tuesday is the largest dollar unlock. And China’s Golden Week holiday runs through October 7, keeping Asian cash markets thin into midweek.
The Macro: FOMC Minutes Offer More Detail
With the September jobs report already in hand, attention turns to FOMC minutes from the September 15–16 meeting, due Wednesday, October 7 at 2:00 p.m. ET — the meeting at which the Fed raised its policy rate to a 3.75%–4.00% target range. The minutes could provide additional detail on how policymakers assessed inflation, employment and the appropriate path for monetary policy at that meeting. However, the release is not a new rate decision.
The Fed’s calendar shows that the next FOMC meeting is scheduled for October 27–28, meaning there is no scheduled rate-setting meeting this week.
The rest of the data is second-tier but worth watching. Monday brings the ISM Services PMI for September (services are roughly 80% of U.S. GDP) and the S&P Global services final. Tuesday has the August trade balance. Thursday delivers weekly jobless claims and the ECB’s account of its September meeting, with China’s markets reopening after Golden Week. Friday closes with the University of Michigan consumer sentiment preliminary for October, including closely watched inflation expectations. September CPI is not until next week (October 14).
TOKEN2049 Singapore Takes Center Stage
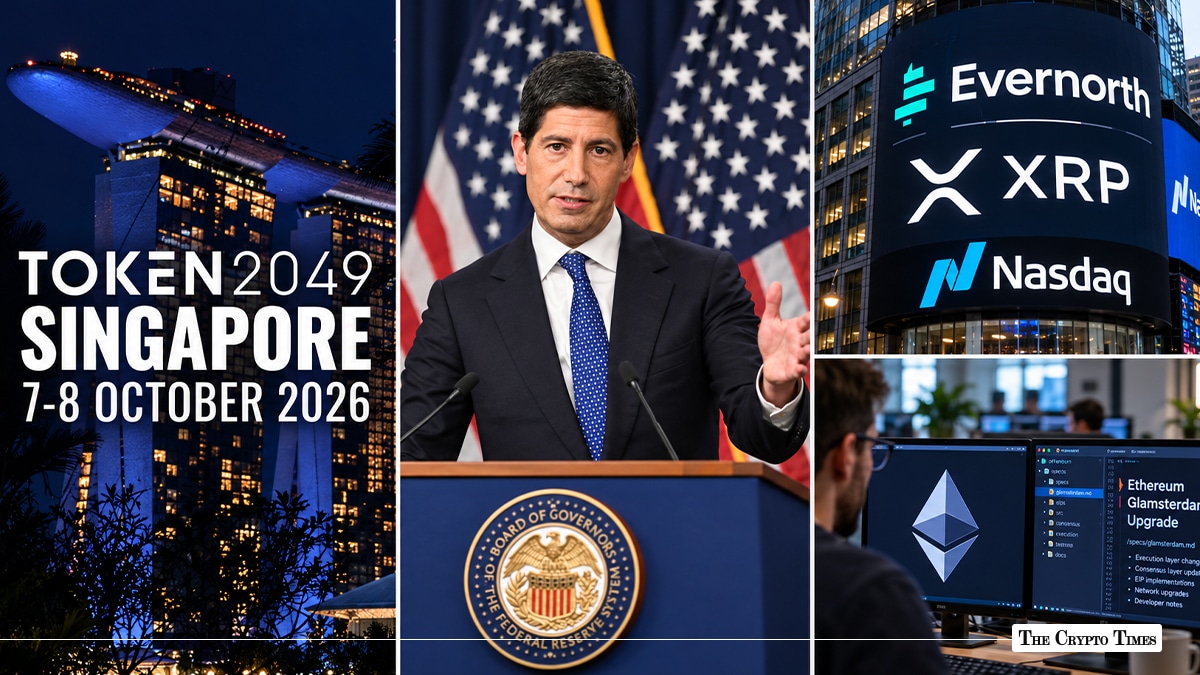
The industry’s calendar this week belongs to TOKEN2049 Singapore (October 7–8) at Marina Bay Sands, one of the largest gatherings in crypto, with organizers citing more than 25,000 attendees and a week of side events running October 5–11. The speaker roster spans crypto-native and traditional finance, reportedly including Hyperliquid’s Jeff Yan, Nasdaq’s Adena Friedman, Franklin Templeton’s Jenny Johnson, BitMine’s Tom Lee and Base’s Jesse Pollak.
For crypto markets, the conference provides a concentrated setting for announcements, partnerships and industry discussions, but individual announcements should be assessed on their own terms rather than assumed to have a direct market impact.
Evernorth’s XRP Treasury Hits Nasdaq
Evernorth is expected to begin trading on Nasdaq under the ticker XRPN, after Armada Acquisition Corp. II shareholders approved its merger on September 30. The Crypto Times has tracked the deal from when its Form S-4 took effect through the shareholder vote that cleared its path to a larger XRP treasury.
Evernorth says it expects to hold roughly 473 million XRP and describes itself as the largest publicly traded pure-play XRP treasury — a characterization that is the company’s own, and a listing still subject to customary closing conditions. The debut is the latest in the broader “digital-asset treasury” trend, in which listed vehicles raise capital to accumulate a single token. These structures give equity investors leveraged exposure to the underlying asset but carry the risks of that leverage and of trading at a premium or discount to the crypto they hold; nothing here is a recommendation.
Ethereum’s Glamsterdam Moves to Sepolia
On the protocol side, Ethereum’s Glamsterdam upgrade activates on the Sepolia testnet on Tuesday, October 6, at 13:53 UTC, per the Ethereum Foundation. The upgrade introduces enshrined proposer-builder separation (EIP-7732), block-level access lists (EIP-7928) and gas repricing, and node operators will need updated execution and consensus clients. Importantly, this is a testnet milestone: the mainnet activation remains unscheduled, with a target only of Q4 2026 and no date set. It is an infrastructure step, not a price event.
The Unlock Calendar: HYPE Leads, With Nuance on ENA
Token unlocks are scheduled vesting events, but they do not necessarily mean tokens will be sold. Vested tokens can remain in insider, community or foundation wallets rather than entering the market. Two events this week also require additional context.
Hyperliquid’s HYPE unlock on Tuesday, October 6 is currently listed among the week’s largest scheduled unlocks by estimated dollar value, but the estimate varies by Tokenomist snapshot. Tokenomist’s monthly card showed the day’s unlock at about $856 million, while its more recent seven-day view put the figure closer to $340 million, or roughly 1.7% of supply. The difference means the dollar value should be treated as an estimate rather than a fixed amount.
Ethena’s ENA carries an important distinction on Monday, October 5. Alongside a Tokenomist estimate of roughly $43 million in scheduled unlocks, a separate contractual development involving StablecoinX concerns approximately 3.03 billion ENA, or about 20% of supply. The 48-month lock-up on those tokens is scheduled to be waived on October 5. However, the waiver does not itself mean those tokens will be sold or transferred. Any sale, transfer or hedge would still require written consent from the Ethena Foundation, five business days’ notice and remain subject to the foundation’s right of first refusal. The contractual waiver should therefore be distinguished from a market liquidation event.
Smaller scheduled unlocks follow through the weekend — MOVE (about 1.5 million tokens) on Friday, BABY (about 1.9 million) on Saturday, and Aptos (about $9 million, or roughly 1.3% of market capitalization) on Sunday. Separately, Sanctum has announced plans to burn about 259 million tokens as part of its transition from CLOUD to SANC. The project said the move would reduce total supply by roughly 25%, although the burn figure should be checked against Sanctum’s latest official announcement before being treated as a completed supply reduction.
The Bottom Line
This is a conference-and-context week rather than a decision week. The soft jobs print has already done the heavy lifting on rate expectations; Wednesday’s minutes will color, not change, that picture. The real action is in Singapore, where a week of announcements will set narratives, and in the corporate arena, where Evernorth’s XRP-treasury debut tests institutional appetite for single-asset vehicles. The Crypto Times makes no forecast on prices, the Fed path or any listing.
Also Read: Singapore Crypto Activity Rises 55% as Institutional Activity Surges 94%