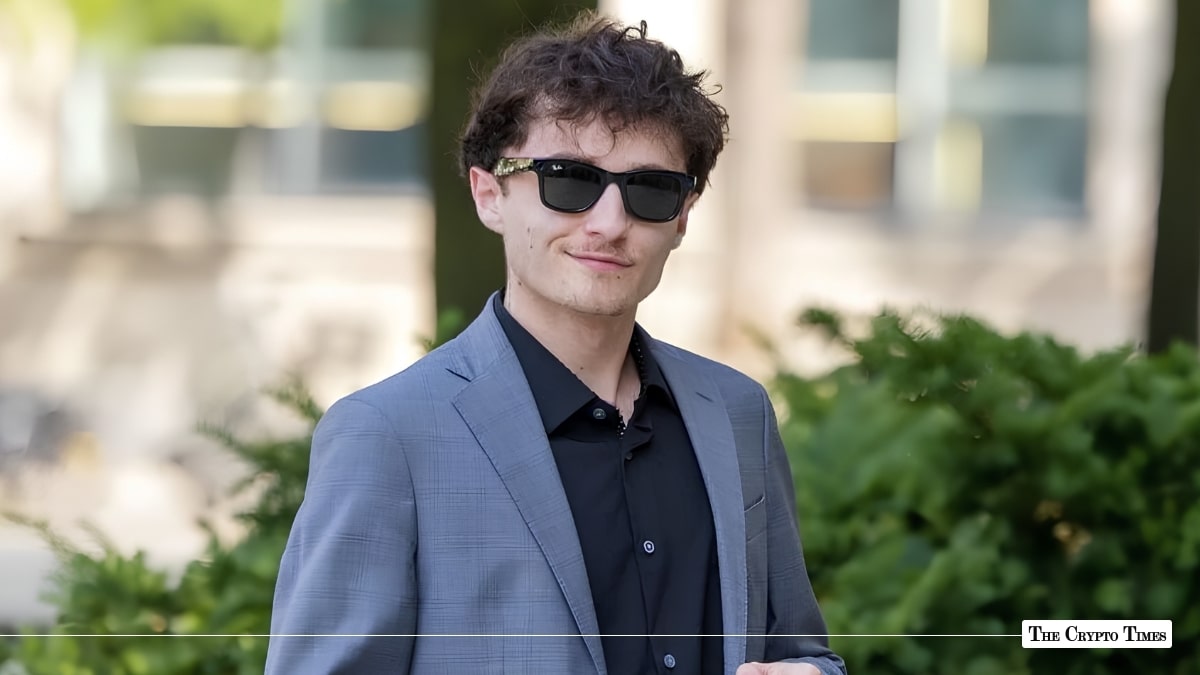
Self-proclaimed “Crypto King” Aiden Pleterski’s forensic audit now shows almost none of his investors’ money ever touched a trading platform. The 27-year-old is on trial in Toronto for fraud and money laundering after allegedly taking $36.3 million from investors who believed they were funding foreign exchange and crypto trades.
According to a local report, testimony from an Ontario Securities Commission accountant this week laid out, for the first time in court, exactly where that money actually went.
Albert Ciorma, a senior forensic accountant with the OSC, told Toronto’s Superior Court on Friday that Pleterski spent more than $16.3 million of investor funds on himself, while paying out roughly the same amount to other investors in payments that mirrored a classic Ponzi structure.
What the Accountant Testified
Ciorma’s forensic audit found that none of the funds Pleterski received from investors were ever sent to FXChoice, the trading platform his contracts specified. Only about $113,000 total went to any other foreign exchange or cryptocurrency platform.
Instead, Ciorma testified, Pleterski spent roughly $5.6 million on luxury vehicles, $4.9 million on credit card bills, $870,000 on travel and private jets, $598,000 on security, and gave nearly $3.7 million to his parents. He also took $609,000 in cash advances from a credit card. Those expenses alone total more than $16.3 million.
Pleterski paid out a further $16.1 million to investors from funds received from other investors, according to Ciorma—the mechanism at the center of the Crown’s fraud case. Crown prosecutor Scott Patterson walked the accountant through dozens of pages of bank records in court, pointing to a recurring pattern: “We see the same pattern, money in and expenses to credit cards,” Patterson said, referencing transactions from spring 2021.
The records also showed spending on hotels, designer clothing, and jewelry, along with more than $84,000 for a Miami property rental in October 2021 and $95,200 paid to the Toronto Blue Jays in April 2022.
The $311 Million That Wasn’t
Two investors who testified earlier in the trial described seeing a video of a Pleterski FXChoice account showing a balance of $311 million in spring 2022. Asked whether he had seen anything close to that figure in the accounts he reviewed, Ciorma told the court: “No, just what we’ve seen today.”
One of those investors, Mitchell Learning, later gained access to Pleterski’s email and found the FXChoice account had in fact been closed. Learning testified that Pleterski confessed to him directly that he had lost investor funds and had been using money from new investors to pay out earlier ones — the Ponzi structure that Ciorma’s audit now corroborates with bank records.
The Case So Far
Pleterski, now 27, was charged with fraud over $5,000 and money laundering in May 2024, following a joint investigation by the Ontario Securities Commission and Durham Regional Police, which has called it the force’s largest-ever fraud investigation.
He has pleaded not guilty, and the allegations remain unproven in court. His four-week jury trial, for which he is representing himself after a judge denied his request to delay proceedings and hire a lawyer, began October 5 in Toronto’s Superior Court and is expected to continue through the rest of the month.
Nearly a dozen investors have already testified to giving Pleterski more than $6 million collectively, describing promised weekly returns of 2% to 10% on foreign exchange and crypto trades, delivered via text updates from Pleterski.
Most said they never recovered any of their money. A separate bankruptcy proceeding that began in 2022, after investors petitioned to force Pleterski into bankruptcy, found he had invested less than 2% of the roughly $40 million he received—a figure Pleterski has disputed.
A Familiar Pattern
The spending breakdown presented in court, luxury cars, private jets, credit card bills, and cash to family, follows a template that has recurred across crypto’s highest-profile fraud cases. Sam Bankman-Fried was convicted in 2023 of diverting FTX customer funds toward a $35 million Bahamas penthouse and other personal spending while running the exchange; Terraform Labs founder Do Kwon faced similar allegations tied to the collapse of TerraUSD and Luna.
In each case, prosecutors built their claims the way Ciorma did in Pleterski’s trial: tracing bank and exchange records to show money moving away from the investments a founder claimed to be making and into personal accounts.
When the Fraudster Becomes the Target
Pleterski’s case carries an added dimension that sets it apart from other crypto fraud trials: in December 2022, he was himself kidnapped and held for three days by men demanding a ransom, at least one of whom was an investor who had lost money to his scheme. One of his alleged kidnappers has since pleaded guilty.
The incident sits within a broader pattern security researchers call “wrench attacks”—physical coercion used to force crypto holders to hand over funds or access. Blockchain security firm CertiK recorded a 33% year-over-year rise in documented wrench attacks in the first half of 2026 alone.
Crypto executives and known holders have increasingly become targets of such attacks, regardless of whether, as in Pleterski’s case, the underlying wealth attackers believe they are owed was ever real.
Also Read: Who Is Richard Heart? From HEX Crypto Millions to Istanbul Detention